BOSTON — To reshape product portfolios for long-term success, medtech companies are likely to stay focused on tuck-in M&A and divestitures, executives said this week at AdvaMed’s The MedTech Conference.
“Scale is not a strategy,” said Zimmer Biomet CEO Ivan Tornos, speaking on a Tuesday panel. “Ten, 15 years ago, all of us were going to be bigger. I'm not going to go through all the examples. Most of them have not worked out.”
Zimmer’s acquisition strategy begins with the problem that the company is trying to solve, Tornos said. In orthopedics, that can be about efficiency, managing infection or delivering best-in-class outcomes.
“We start with the strategy, then we look at the financial business case,” said Tornos. Zimmer today looks at deals that are under $2 billion in price, he said. The company may pay slightly more for an interesting asset. Its recent purchases have included pain relief device maker Pacira BioSciences for up to $140 million, robot developer Monogram Technologies for $177 million and implant maker Paragon 28 for about $1.1 billion.
Deciding which capabilities to acquire and which to build internally takes “intellectual honesty” about a company’s strengths and needs, said Tornos. When he joined Zimmer in 2018, most of its capabilities were biomechanical. The company wanted to embrace digital technologies and robotics, he said, and now the mix is 50-50.
On the flip side, sometimes a divestiture is necessary to help a business thrive, said Rachel Ellingson, chief strategy and corporate development officer at Solventum.
When Solventum was spun out of 3M more than two years ago, it had strong businesses in attractive markets, but the new company also carried a lot of debt. Solventum’s first portfolio move was to sell its purification and filtration business to Thermo Fisher Scientific for about $4.1 billion.
The deal allowed Solventum to pay down debt and then acquire wound care company Acera Surgical for up to $850 million.
“Acera Surgical was very much in the space we were focused on,” said Ellingson. “We would not have been able to do that had we not done a divestiture because we wouldn't have had the financial flexibility.”
Solventum is now planning to separate its health information systems business.
“The leading innovations, sometimes they come from internal R&D, oftentimes external, and so we try to place bets across those three spectrums of internal and M&A and venture.”

Mike Mahoney
Boston Scientific CEO
Ellingson predicted the medtech industry will see more tuck-in acquisitions and portfolio reshaping.
“I don't really think you're going to see large-scale consolidation,” said Ellingson. “Tuck-in M&A is closer to the core. Over time, most of us have all seen that that's where you get the most success. You know those areas better. You know the businesses better. You know the customers better. You know the questions to ask in diligence. With that knowledge, you reduce the level of risk.”
Portfolio reshaping will continue because capital remains “finite” for all companies, she said.
“You have to make decisions around where to allocate your resources,” Ellingson said. “If you find there are areas inside your company that might not be getting the resources they need, you should ask the question whether you're the right owner.”
Boston Scientific’s strategy
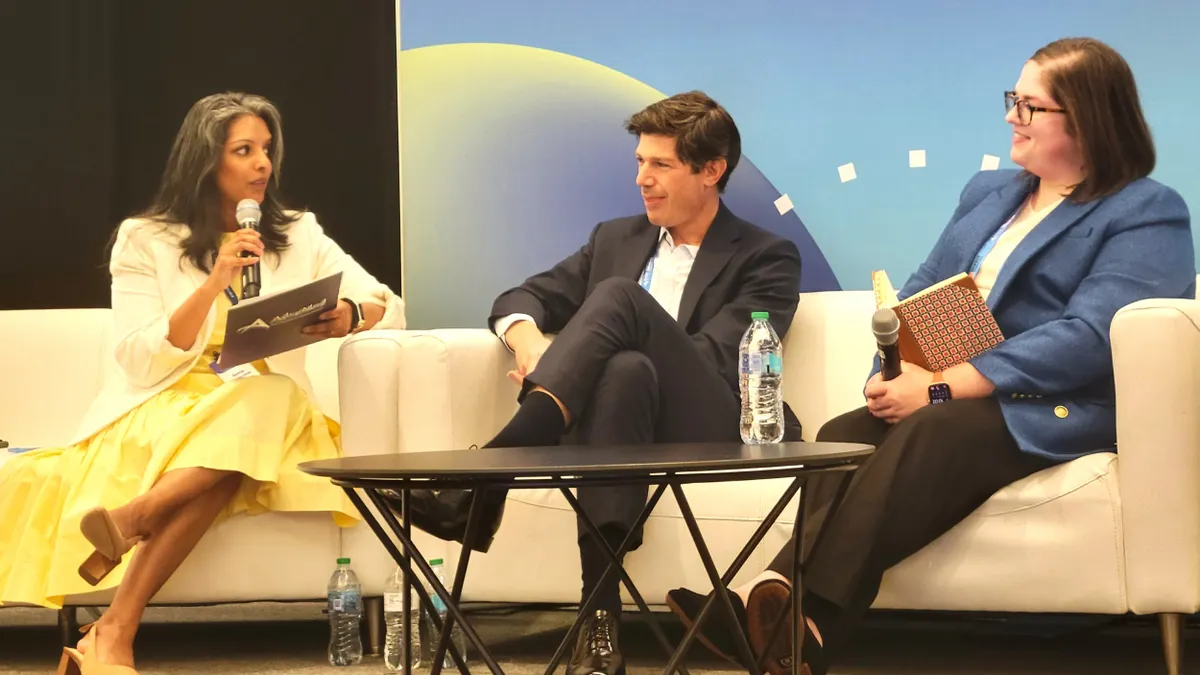
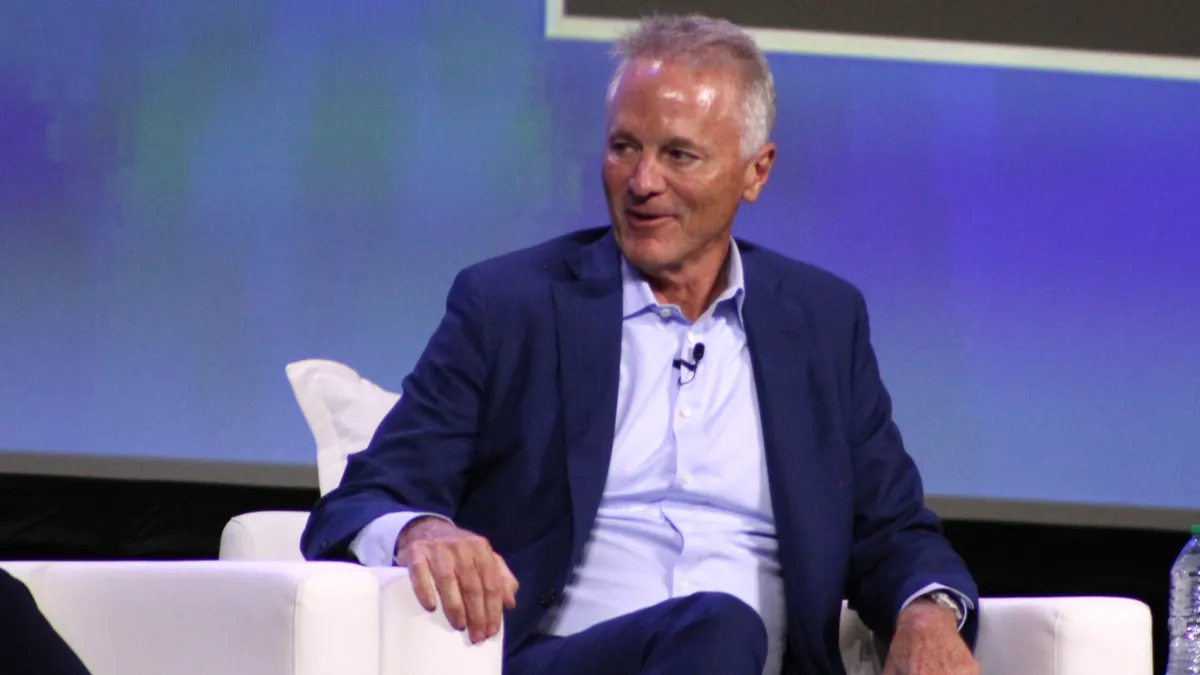
At a Monday panel, Boston Scientific CEO Mike Mahoney emphasized the importance of investing for the long term. Boston Scientific spends a lot of money on R&D, has done a number of acquisitions over the years and has an active venture portfolio, Mahoney said. The goal is to create a differentiated portfolio and category leadership, even if the growth platforms aren’t going to launch for three to four years.
“The leading innovations, sometimes they come from internal R&D, oftentimes external, and so we try to place bets across those three spectrums of internal and M&A and venture,” he said. “The venture portfolio gives you gray hair sometimes because maybe those companies don't work out. But I have so much respect for the entrepreneurs and the small companies here to take the risk to advance science.”
J.P. Morgan analyst Robbie Marcus, also on the panel, offered his perspective on what will attract investors to the medtech sector.
“Investor interest in medtech is at an all-time high, even as the sector has underperformed the broader stock market,” Marcus said. “It may not feel like that, but around the world, investors are absolutely looking at medtech valuations here, the entry points.”
Like many other sectors, medtech is vying with AI companies for investor dollars. “Quite frankly, they're so large. The stocks have done so well. They're growing so quickly. It's just sucked up all the capital in the market,” said Marcus. “And that's not medtech-specific. That's the market in general right now.”
Medtech is a highly growth-focused and innovative sector, said Marcus, and his financial models point to sales growth for the industry across the board in 2027.
“The best thing that medtech companies can do is to deliver new product launches, deliver new innovation, give investors reasons to believe in accelerating sales growth in the future,” he said. “Investors will come.”